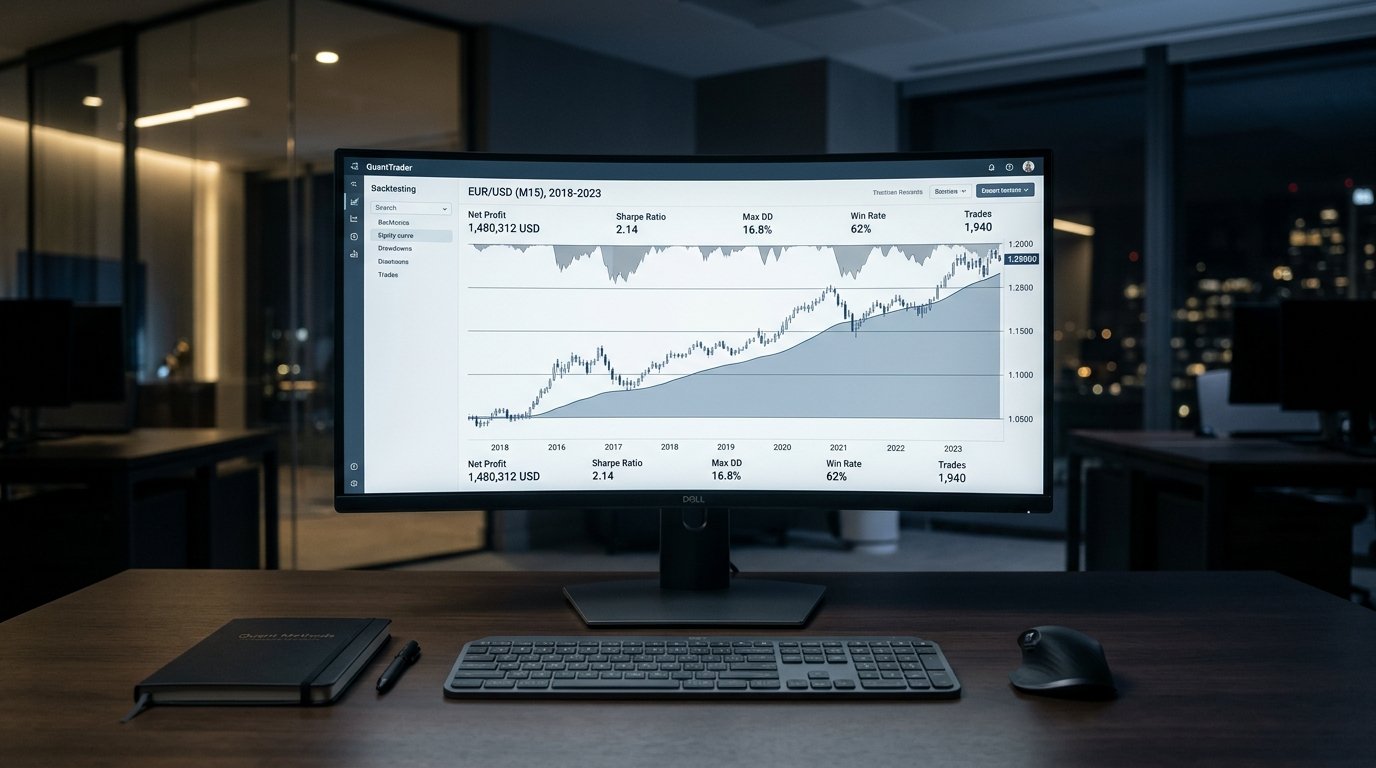
When you run a strategy backtest in MetaTrader or record trades manually in a spreadsheet, you are greeted by a table filled with statistical data and technical terms.
Beginners often feel overwhelmed and end up looking at only one figure: Total Net Profit. However, net profit rarely tells the whole story. A strategy can generate $5,000 in net gains while carrying an extreme risk of blowing up the account along the way.
To evaluate any systematic strategy objectively, here are the five core statistical metrics you need to understand before trusting a performance report.
1. Win Rate and Risk-to-Reward (RR) Ratio
These two metrics form the foundation of trading mathematics and must always be examined together:
- Win Rate: The percentage of closed trades that resulted in a profit relative to the total number of trades taken.
- Example: If a strategy wins 60 out of 100 trades, the Win Rate is 60%.
- Risk-to-Reward Ratio (R:R): The relationship between the potential loss defined by your Stop Loss (Risk) and the potential gain targeted by your Take Profit (Reward).
- Example: If you risk $50 on a trade to pursue a $100 target, your ratio is 1 : 2.
Traders often obsess over finding high win-rate systems (70% or 80%). However, a strategy with a modest 40% win rate can remain consistently profitable over time if it maintains a solid 1:2 or 1:3 risk-to-reward ratio. Conversely, an 80% win rate is meaningless if a single large loss erases the profits accumulated from five previous winning trades.
2. Profit Factor
Profit Factor measures how effectively a strategy generates gains relative to the losses it incurs.
Profit Factor = Total Gross Profit / Total Gross Loss
Here is a practical guideline for interpreting the result:
- Below 1.0: The system is unprofitable. Total losses exceed total gains.
- 1.0: Breakeven. The system generates no net gain and loses money to spreads and commissions.
- 1.3 to 1.7: Healthy, realistic, and robust for live market execution over a large sample size.
- Above 3.0: Approach with caution. Extremely high numbers in historical testing often point to curve-fitting (over-optimizing parameters to fit historical noise) or an insufficiently small trade sample.
3. The Three Types of Drawdown
Drawdown reflects the depth of equity decline an account experiences from a given reference point. In MetaTrader strategy reports, drawdown is categorized into three metrics:

- Absolute Drawdown: The largest decline below the initial deposit balance. It answers: “Did my starting capital drop, and by how much?” If your account balance immediately moves upward and never drops below your starting deposit, Absolute Drawdown is zero.
- Maximal Drawdown: The largest drop in monetary value (currency amount) from a peak to the subsequent trough. It reveals the maximum amount of cash that temporarily disappeared during testing.
- Relative Drawdown: The largest peak-to-trough drop expressed as a percentage (%). This is the most objective measure of risk because a $3,000 drawdown on a $5,000 account (a 60% loss) is devastating, whereas a $3,000 drawdown on a $100,000 account (a 3% dip) is routine.
4. Consecutive Wins and Consecutive Losses
These metrics track uninterrupted winning and losing streaks:
- Consecutive Wins: The maximum number of winning trades that occurred in a row before a loss appeared.
- Consecutive Losses: The maximum number of losing trades that occurred in a row before a winning trade appeared.
For any systematic trader, Consecutive Losses is the most critical metric. It defines your historical worst-case scenario. Knowing that your system has historically experienced 5 or 6 consecutive losses helps you size your positions conservatively, preventing account ruin during unavoidable drawdown periods.
Summary
Evaluating a strategy report is not about finding perfection. Every real-world trading method experiences losing streaks and periods of equity drawdown.
Understanding these core metrics allows you to assess a strategy objectively through mathematics rather than emotional expectations.
In our next guide, Connecting the Dots of Backtesting, we examine how these metrics interconnect, and how they determine both your capital requirements and psychological endurance in live markets.
Which metric do you prioritize when evaluating a backtest report? Do you look at drawdown first, or do you focus on the risk-to-reward balance? Share your perspective in the comments below.
To see real backtest metrics analyzed in detail—including surviving a 9-loss streak with a 30.5% win rate—explore our breakdown in Surviving the Chop on Gold M15.
Official Automated Expert Advisor • 100% Free
Automate This Strategy with the Round Number Gold EA
Why calculate Round Number levels and manage pending orders manually? Download the official MT4 Expert Advisor with embedded 1:3 RR math, automatic pending order purge, and the exact backtested preset (+339% gain on Exness-Real33).
Leave a Reply